1. It is flagged
Spray foam usually comes up because a surveyor or valuer reports it, often when you sell or remortgage. At a glance:
- Highest concern
- Closed-cell foam on the underside of the roof
- Lower concern
- Foam on a loft floor, or a report a lender accepts
- What lenders say
- A quarter of the biggest lenders surveyed would not lend on roof spray foam (BBC, Nov 2024)
- Removal cost
- About £3,200 for a three-bed detached roof (Checkatrade, quoted by the House of Commons Library); get an itemised quote
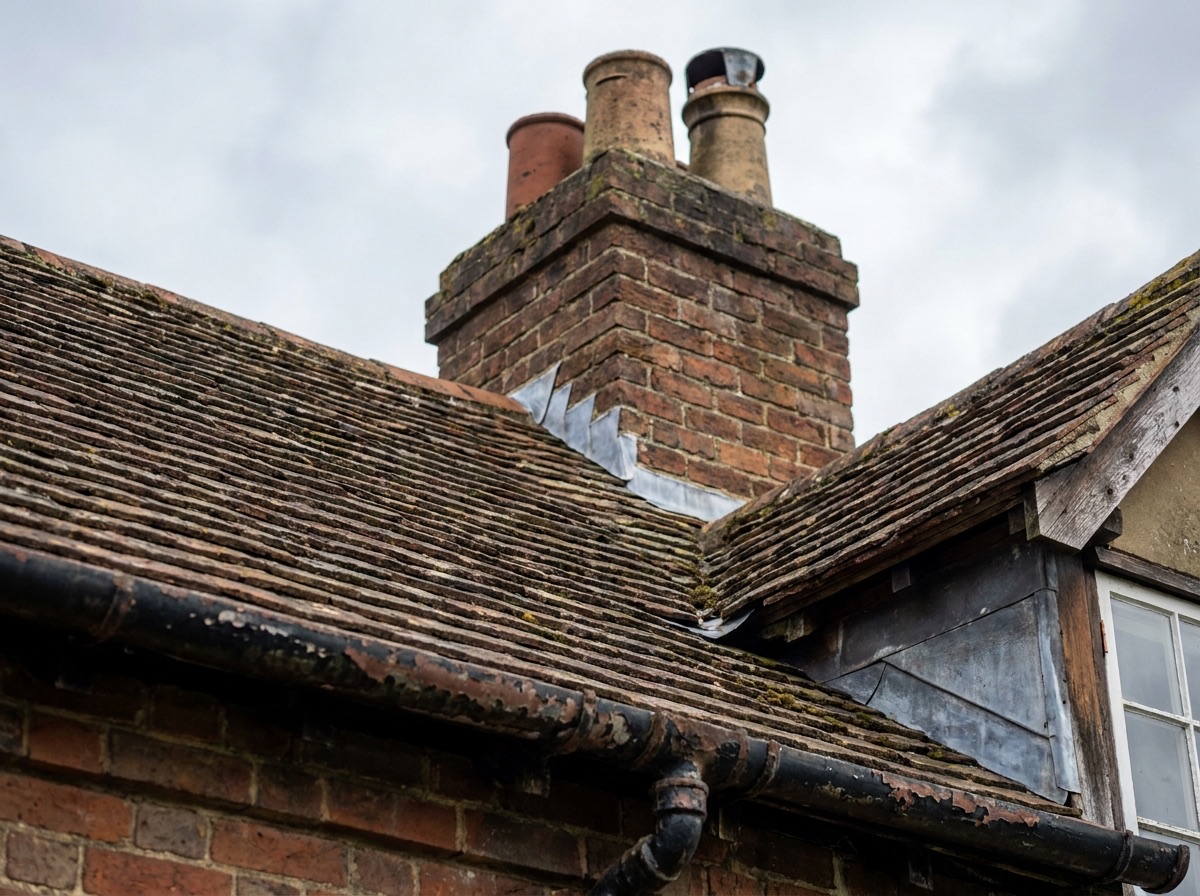
2. What it means: why lenders react to spray foam
The problem is not the insulation itself but what it can hide. Closed-cell spray foam applied to the underside of a roof can restrict the ventilation a roof needs, trap moisture against the timbers, and make it impossible for a surveyor to inspect the rafters for rot. Because a lender's security is the property, anything a surveyor cannot sign off makes the home a higher risk to lend against.
Open-cell foam is softer and more vapour-open, and a very limited number of lenders will consider a property with it. Closed-cell foam on a roof is the case queried most. Foam that is not on the roof, for example on a loft floor, is generally viewed differently. This is why the foam type and its location drive how a lender responds. For the difference in full, see our open-cell vs closed-cell guide.
3. Who decides, and what they look at
Four people shape the outcome. Only one of them is you.
Your surveyor or valuer
Notices it and reports it
They note the foam type and where it is. They cannot sign off what they cannot inspect.
Your lender
Decides whether it will lend
Policies vary. Some decline outright, a very limited number consider open-cell foam, and many will lend where there is a professional inspection report or once the foam is removed and the roof certified.
Ask your lender: what report they will accept, before you book any work.
A qualified inspector
Writes the report a lender will assess
A qualified surveyor or a Property Care Association member can inspect your individual roof under the protocol published in March 2023. Where foam is removed, lenders commonly ask for an RICS chartered surveyor to confirm complete removal.
You
Choose the route
Get a professional inspection before assuming removal is the only option. What your lender requires should be confirmed before booking any work.
4. Your options: do you actually need to remove it?
Not always. In March 2023 the Property Care Association published an inspection protocol so that a surveyor can assess the condition of your individual roof, rather than a lender declining simply because foam is present. Where a lender queries the foam, there are two usual routes:
A. Inspect
A professional inspection report, from a qualified surveyor or a Property Care Association member, that a lender will accept; or
B. Remove
Removal of the foam, followed by a survey confirming the roof is sound. Lenders commonly ask for a survey by an RICS chartered surveyor confirming complete removal and that no further remedial work is required.
Which route applies depends on the foam type, its location, your documentation and your specific lender. Get a professional inspection before assuming removal is the only option.
5. The right help: what removal involves and what it costs
Removal is a specialist job, done largely by hand: the foam is scraped and stripped from the rafters and felt, the timbers are checked for damage, the waste is cleared, and a removal report confirming the roof condition is produced. The House of Commons Library (January 2026) quotes Checkatrade's estimate of around £3,200 to remove spray foam from the roof of a three-bedroom detached house, but the real figure depends on the foam type, the roof size and access, so get an itemised written quote.
For detail, see the removal process step by step, what drives the cost, and the UK spray foam and mortgages numbers.
Start with a professional inspection. The kind of professional that matters is a qualified surveyor or a Property Care Association member, and for removal reports an RICS chartered surveyor. We do not run our own vetting of firms: you can check accreditation yourself, free, on the official register.
Questions people ask
Does spray foam always stop you getting a mortgage?
No. The concern is mainly closed-cell foam on the underside of a roof, because it can trap moisture and hide the timbers. Some lenders decline outright, a very limited number consider open-cell foam, and many will lend where there is a professional inspection report or once the foam is removed and the roof certified. Policies vary, so a professional inspection is the sensible first step.
Do I have to remove spray foam to sell or remortgage?
Not always. Where a lender queries it, the usual routes are a professional inspection report a lender accepts, or removal followed by a survey confirming the roof is sound. Lenders commonly ask for a survey by an RICS chartered surveyor confirming complete removal and that no further remedial work is needed. What your lender requires should be confirmed before booking any work.
How much does spray foam removal cost?
There is no single or official price. The House of Commons Library (January 2026) quotes Checkatrade's estimate of around £3,200 (£40 per square metre) to remove spray foam from the roof of a three-bedroom detached house. The real figure depends on the foam type, the roof size and access. Closed-cell foam bonded to the felt costs more to remove. Get an itemised written quote from a specialist who has inspected the roof.
Is VettedHome a lender or a removal firm?
Neither. VettedHome is independent. If you ask for help, we send your request to the firm you choose or to up to 3 removal firms that cover your area, so they can contact you. We do not run our own vetting of firms, and VettedHome is free to use.
Sources
- RICS spray foam consumer guide (2023): rics.org
- Property Care Association, spray foam homeowner guidance: property-care.org
- House of Commons Library, spray foam insulation and mortgages: commonslibrary.parliament.uk
Keep reading
Related on VettedHome
Editor, VettedHome
Adam leads VettedHome's editorial coverage of UK home services. He is the founder and managing director of Muswell Rose, the commercial strategy and modern systems business behind a portfolio of UK information sites, and he researches and writes the plain-English guides that help homeowners choose between installers and trades, drawing on the standards set by the relevant bodies for each job, such as Gas Safe Register, NICEIC, MCS, TrustMark and the Property Care Association. He is clear about what to check before any work starts.
AI-assisted check